Payroll Taxes: What They Are and How to Calculate Them
Updated on October 6, 2026 | 18 min. read


Payroll taxes are the taxes you withhold from your employees’ paychecks, plus the taxes you owe as an employer on top of their wages. You send both to the government to fund programs like retirement benefits, health coverage, and unemployment insurance.
Whether you have one employee or five, you calculate, withhold, and remit these taxes yourself, and mistakes can lead to penalties. This guide shows you which payroll taxes apply to your business, who pays them, and how to calculate a paycheck from gross to net pay.
🌟 KEY TAKEAWAYS

Every paycheck creates an obligation to withhold taxes from your employee and pay taxes you owe as an employer.
Calculating payroll taxes involves subtracting withholdings and deductions from gross pay to get to net pay.
Your deposit schedule determines when the money is due, and late deposits cost 2% to 15% of the unpaid amount.
What are payroll taxes?
Payroll taxes are taxes that both you and your employees pay on wages. You withhold them from each worker’s paycheck and remit them to the U.S. Treasury and some state agencies on the employee’s behalf. Withholding lets employees pay their tax liabilities gradually throughout the year rather than all at once.
You submit the taxes you withhold on a set schedule, along with your employer's share of payroll taxes. The law requires you to withhold these taxes from employee paychecks.
Here’s who pays what across the taxes you handle through payroll:
Employees pay: Federal, state, and local income taxes. You withhold from each paycheck.
You and your employees share: Social Security and Medicare taxes. Each of you pays 7.65% of wages. You withhold the employee’s half from their paycheck and pay your matching half.
You pay: Federal unemployment tax (FUTA) and, in most states, state unemployment insurance (SUI). These never come out of an employee’s paycheck.
Payroll tax vs. income tax
Payroll taxes fund specific programs. Social Security and Medicare taxes fund retirement and health benefits, and unemployment taxes fund unemployment benefits for out-of-work employees. Federal, state, and local income taxes go into the government’s general fund, and the amount depends on each employee’s income and Form W-4.
Income tax withholding runs through payroll, so it feels like a payroll tax. It appears on the employee’s pay stub, and you report it on the same federal employment tax return as Social Security and Medicare. The difference is who owes it. Your employee owes income tax on their earnings, and you collect it. You owe your own share of payroll taxes, which increases the total cost of hiring.
Types of payroll taxes
The following seven items show up on most payrolls. Two are income taxes you withhold for employees. The other five are payroll taxes and related costs you owe, your employees owe, or you split.
Federal income taxes
Employees must pay federal income taxes, but you’re responsible for calculating, withholding, and remitting these taxes.
Each employee pays federal income taxes depending on their filing status and income level. The amount you withhold depends on the details they give you on Form W-4.
State and local income taxes
Most employees also owe state (and sometimes local) income tax, and you withhold and remit it the same way. Nine states don’t tax wages, including Alaska, Florida, Nevada, New Hampshire, South Dakota, Tennessee, Texas, Washington, and Wyoming. You may still owe other payroll taxes there, such as state unemployment insurance.
In every other state, rates and rules vary, so check with your state and local tax agencies before your first payroll.
Social Security and Medicare taxes
The Federal Insurance Contributions Act (FICA) requires Social Security and Medicare taxes. You and each employee pay half:
- Social Security: 6.2% for each, for a combined 12.4% on wages up to $184,500 in 2026
- Medicare: 1.45% each, for a combined 2.9% on all wages with no cap
That adds up to 7.65% each and 15.3% combined. You withhold the employee’s 7.65% from each paycheck and send it with your matching share.
Employees also owe an Additional Medicare tax of 0.9% on wages above $200,000 in a calendar year. You start withholding it once you pay an employee more than $200,000, but you don’t match it.
Federal unemployment tax (FUTA)
The Federal Unemployment Tax Act supports the unemployment system that pays benefits to eligible workers who lose their jobs. You pay it yourself and never withhold it from employee pay.
FUTA applies to the first $7,000 you pay each employee in a year, at 6.0% before credits. If you pay your state unemployment insurance on time, you get a credit of up to 5.4%. That brings your effective rate to 0.6%, or up to $42 per employee.
Employers in states that haven’t repaid federal unemployment loans lose part of that credit and pay more. The US Department of Labor publishes a list of the affected states on its FUTA credit reductions page.
Federal Unemployment Tax
The Federal Unemployment Tax Act (FUTA) states that employers must pay a tax that funds unemployment systems.
These systems offer support to people who lose their jobs. If an employee loses their job, they can claim unemployment benefits designed to help them until they find another job.
The majority of employers pay both federal and state unemployment taxes. But these taxes aren’t deducted from employee paychecks. Instead, employers have sole responsibility for paying this tax.
For this reason, it may appear that the FUTA tax isn’t a payroll tax. But that isn’t the case. The amount the employer pays depends on an employee’s wages, making FUTA a payroll tax. Currently, employers only pay federal unemployment taxes up to a fixed threshold of $7,000 per employee.
Some employers may also claim a credit against their FUTA tax obligations. This usually applies if the employer has to pay into a state unemployment fund. The credit varies depending on the state.
State unemployment insurance (SUI)
State unemployment insurance, also known as SUI or SUTA, is the state-level counterpart to FUTA. It funds your state’s unemployment benefits for eligible workers. In most states, you pay it yourself and don’t withhold it from employee pay.
Rates and wage limits vary by state, so check your state’s rules before you calculate SUI.
State disability insurance
Five states require disability insurance programs that replace part of an employee’s pay when a non-work-related illness or injury keeps them from working. Those states are California, Hawaii, New Jersey, New York, and Rhode Island.
California and Rhode Island fund their programs through employee paycheck deductions. Hawaii, New Jersey, and New York combine employee and employer contributions.
If you have employees in one of these states, check the state’s rules for rates and how much you withhold.
Workers’ compensation
Workers’ Compensation insurance covers medical costs and lost wages for employees who get hurt or sick because of their job. Unlike state disability insurance, it covers work-related injuries.
In most states, you pay for it based on your payroll and job classifications. State rules vary on who must buy coverage, so confirm your requirements before you hire.
Payroll tax rates at a glance
Keep this table handy when you run payroll. It shows the 2026 rate for each tax, who pays it, and the wage limit where one applies.
Tax | Employee rate | Employer rate | Wage base or cap | Who pays |
|---|---|---|---|---|
Social Security | 6.2% | 6.2% | $184,500 | You and your employee |
Medicare | 1.45% |
| None | You and your employee |
Additional Medicare | 0.9% | None | Wages over $200,000 | Employee |
FUTA | None | 0.6% after credit (6.0% before credit) | First $7,000 | You |
SUI | Varies | Varies | Varies by state | You in most states |
Federal income tax | Varies (See Publication 15-T) | None | None | Employee |
State and local income tax | Varies | None | None | Employee |
State disability insurance | Varies | Varies | Varies | Varies by state |
What’s new for the current tax year
Two new federal deductions for tips and overtime run from 2025 through 2028, and starting in 2026 they change what you report on Form W-2. They don’t change what you withhold.
New W-2 reporting requirements
The 2026 Form W-2 instructions add three items
- Box 12, code TP: the total cash tips an employee reported to you
- Box 12, code TT: the total qualified overtime you paid, which is the “half” in time-and-a-half that the Fair Labor Standards Act (FLSA) requires
- Box 14b: up to two Treasury Tipped Occupation Codes (TTOCs) for any employee with code TP in Box 12
The form now splits Box 14 into 14a and 14b.
Does this change your withholding?
Tips and overtime are still subject to federal income tax withholding, Social Security tax, and Medicare tax. Employees claim the deductions on their own returns, up to $25,000 for qualified tips and $12,500 ($25,000 for married couples filing jointly) for qualified overtime. You reduce federal income tax withholding only when an employee gives you an updated Form W-4 that estimates the deduction in Step 4(b), per the IRS’s overtime FAQs.
Who these changes affect the most
If you have tipped team members, you report their tips and assign occupation codes. If you have hourly staff, you track overtime by workweek. For most employees, qualified overtime equals FLSA overtime hours over 40, times one-half, times the regular rate. Employees exempt from FLSA overtime have none to report.
If you report a wrong amount, you must file a corrected Form W-2c.
How to calculate payroll taxes
Once you know which taxes apply, you can calculate them by hand in five steps.
Step 1: Gather All Required Employee Documents
Collect these forms from each new hire before you run their first payroll.
Form W-4: Employee’s Withholding Certificate
Every new employee fills out Form W-4. It tells you how much federal income tax to withhold from their paychecks. Employees can also use it to request extra withholding or claim exemption from withholding.
The 2026 version includes a checkbox for employees exempt from federal income tax withholding.
State W-4 (as applicable)
Some states have their own withholding form you can use to calculate state and local income tax withholding. Check with your state’s revenue agency to see whether yours does. If a state doesn’t have a state-specific form, the federal Form W-4 is sufficient.
Direct deposit authorization form
You don’t need direct deposit to calculate payroll taxes. But if you plan to pay by direct deposit, have the employee complete an authorization form. Some employers verify the employee’s bank routing and account numbers with a voided check.
Form I-9: Employment Eligibility Verification
All new employees must complete Form I-9, which confirms they can legally work in the United States. The employee completes Section 1 by their first day of work. You complete Section 2 within three business days of their start date after reviewing documents such as a U.S. passport, Social Security card, and driver’s license.
Step 2: Calculate gross pay
Gross pay is what you owe an employee for the pay period before any taxes or deductions. How you calculate it depends on whether the employee earns an hourly wage or a salary and how often you pay them (monthly, semi-monthly, biweekly, weekly).
Hourly employees
Calculate gross pay for hourly wage employees by multiplying the hours worked during a given period by their hourly wage.
For example, say a laborer on your job site works 40 hours a week at $38 per hour. Their gross pay is $1,520 per week.
You also have to factor any overtime into this calculation. Under the Fair Labor Standards Act (FLSA), you generally pay covered, nonexempt employees at least 1.5 times their regular rate for hours worked over 40 in a workweek. So if the same laborer works 5 hours of overtime, you add $285 (5 hours x $57) to their $1,520, for $1,805 in gross pay that week.
Some states have their own overtime rules, so check yours.
Salaried employees
Employees who qualify as exempt from overtime keep the same gross pay each period, unless they take unpaid leave or get a raise. Exempt status depends on the employee’s job duties and, in most cases, their salary. Divide their annual salary by the number of pay periods in the year.
For example, if a manager in your store earns $65,000 per year and you pay them twice per month, divide $65,000 by 24 (12 months multiplied by 2 paydays per month) to get a gross pay figure of $2,708.33 per pay period.
Add any other pay to gross pay, such as bonuses, tips, commissions, and gifts.
Step 3: Calculate employee tax withholdings
Use each employee’s Form W-4 to calculate withholdings.
Federal income tax (FIT)
FIT withholding depends on the employee’s Form W-4, their taxable wages for the pay period, and how often you pay them. Publication 15-T gives you two ways to calculate it manually:
1. Wage bracket method
Look up the withholding amount in a Publication 15-T table, using the employee’s adjusted wages, filing status, pay frequency, and whether they checked the Step 2 box on their W-4. You adjust wages for the W-4’s Step 4(a) and 4(b) entries. The tables cover a limited amount of wages, generally less than $100,000 a year.
2. Percentage method
This method works for any wage amount. You annualize the employees’ wages, adjust them for their W-4 entries, look up the tentative withholding in an annual table, and divide by your number of pay periods. Publication 15-T includes worksheets and tables for manual and automated payroll systems.
To learn more about these methods, rates, and allowances, see our guide on How to Calculate Withholding Tax.
Social Security and Medicare taxes
FICA taxes cover Social Security and Medicare. You withhold them from every employee unless the employee is exempt.
- Social Security: 6.2% of wages up to the annual wage base ($184,500 in 2026). You pay a matching 6.2% for a combined tax rate of 12.4%.
- Medicare: 1.45% of all wages with no annual limit. You pay a matching 1.45% for a combined rate of 2.9%
- Additional Medicare tax: 0.9% on wages you pay an employee above $200,000 in a calendar year. You start withholding once wages pass $200,000, regardless of filing status. There’s no employer match.
Social Security and Medicare together make up the 15.3% FICA rate. You and your employee each pay 7.65%, so you match the amount you withhold from each employee when you send FICA taxes to the government.
Step 4: Handle payroll deductions
Paychecks often include deductions beyond tax withholding. Voluntary deductions include health insurance premiums, 401(k) contributions, and health savings account contributions. Involuntary deductions include wage garnishments for child support, unpaid taxes, or federal student loans. Subtract both from gross pay to calculate each employee’s net pay.
Step 5: Calculate net pay
Once you know gross pay, tax withholdings, and other deductions, you can calculate net pay.
- Begin with the employee’s gross pay
- Subtract tax withholdings
- Subtract other deductions
- The result is the net pay amount for the pay period
For example, say you have a salaried worker earning $50,000 per year in Florida, where there’s no state income tax withholding. Their filing status is single, they completed only Steps 1 and 5 of their 2026 Form W-4, and you use the wage bracket method.
Here’s how you calculate net pay for this employee:
- You pay the employee twice a month, or 24 times per year: $50,000 / 24 = $2,083.33 gross pay per pay period
- Federal income tax withholding is $160 per paycheck, from the semimonthly wage bracket table in Publication 15-T for wages of $2,080 to $2,100
- Social Security is $129.17 (6.2% x $2,083.33) and Medicare is $30.21 (1.45% x $2,083.33), for a combined $159.38 in FICA taxes
- There are no voluntary or involuntary deductions
- $2,083.33 – $160 – $159.38 = $1,763.95
- Net pay after tax withholding is $1,763.95 per paycheck


Calculate employer payroll taxes
Beyond the taxes you withhold, you owe payroll taxes as an employer. You match the Social Security and Medicare taxes you withhold from each employee, and you pay federal and state unemployment taxes on top of wages. The examples below show how the unemployment taxes work for a small California employer.
State unemployment insurance
State unemployment insurance rates vary by state. In California, new employers pay 3.4% on the first $7,000 of each employee’s wages for the first two to three years. California also charges a separate Employment Training Tax on the same wages.
Say you have 2 employees, and each makes $20,000 per year. Both pass the $7,000 limit, so you calculate SUI as follows:
- $7,000 x 0.034 = $238 per employee
- $238 x 2 = $476
You pay $476 in California SUI for the year.
Federal unemployment tax
FUTA is 6.0% of the first $7,000 you pay each employee. Assuming you qualify for the 5.4% credit, your rate would be 0.6%. Using the same example as above:
- $7,000 x 0.006 = $42 per employee
- $42 x 2 = $84
You pay $84 in FUTA for the year.
Filing and paying payroll taxes
Paying payroll taxes takes two steps, and each has its own deadline.
Deposit schedules and EFTPS
You deposit on one of two schedules:
- Monthly: by the 15th of the following month
- Semiweekly: by the next Wednesday for Wednesday to Friday paydays, and by the next Friday for Saturday to Tuesday paydays
You determine your deposit schedule each year. If your Form 941 taxes for the four quarters ending June 30 of the prior year totaled $50,000 or less, deposit monthly. If the total was over $50,000, deposit semiweekly. New employers start on a monthly schedule.
Deposit federal taxes electronically with EFTPS, which is free.
Returns and year-end forms
- Form 941 is your quarterly return, due April 30, July 31, October 31, and January 31
- Form 944 is an annual alternative if you owe $1,000 or less a year. The IRS must approve use of this form in writing.
- Give employees Form W-2 and file it with Form W-3 with the Social Security Administration by January 31.
Late deposits cost 2% of the unpaid amount if they’re up to 5 days late, 5% at 6 to 15 days late, and 10% after that. The penalty increases if you still haven’t paid more than 10 days after an IRS notice. Late returns add a separate penalty, and interest applies to both.
If you withhold taxes and don’t send them in, the IRS can hold you personally liable.
Payroll taxes when you’re your own only employee
Which payroll taxes apply to you depends on your business structure.
S-corp owners
If you own an S corporation, you’re an employee of your own company. The IRS treats corporate officers as employees for Social Security, Medicare, unemployment, and income tax withholding. Your salary runs through payroll. You can avoid payroll taxes on profits you take as distributions by paying yourself a reasonable salary.
For example, say you own a landscaping company and act as the crew manager. A company like yours would pay a crew manager $60,000, so you set that figure as your reasonable compensation and pay Social Security and Medicare taxes on that amount.
The landscaping company earns $150,000 before your pay, so you take another $50,000 in distributions. You don’t owe self-employment tax on that $50,000, as the IRS treats it as a return on investment.
The IRS doesn’t specify a percentage for reasonable compensation, so document how you chose your number.
Sole proprietors
A sole proprietor can’t go on their own payroll. You pay both halves of Social Security and Medicare as self-employment taxes on Schedule SE. But when you add your first hire, you need to run payroll for their wages. You withhold taxes, match your portion, remit taxes, and file payroll tax forms.
Before you issue their first paycheck, get an EIN, collect their W-4 and I-9, and register with your state.
Household employers
Hiring a nanny or caregiver makes you a household employer. In 2026, Social Security and Medicare taxes apply once you pay a household employee $3,000 in wages, and FUTA applies once you pay them $1,000 or more in a quarter. You report both on Schedule H with your Form 1040 and give your employee a W-2.
Take control of your finances: simplify payroll tax calculations
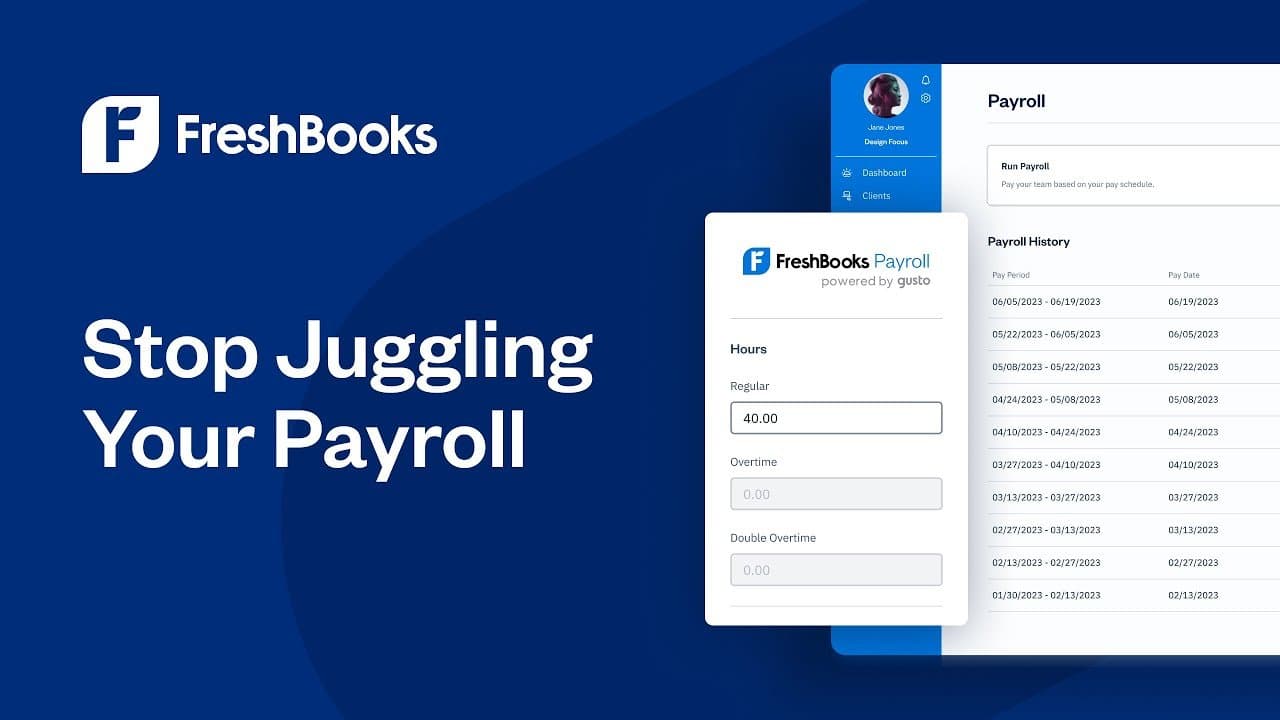
You can handle payroll calculations manually, but that likely means dealing with complicated spreadsheets, recalculating the same formulas every pay period, tracking deposit and filing deadlines, and hoping you picked the right withholding amount. FreshBooks Payroll powered by Gusto takes that work over inside your FreshBooks account.
It calculates the taxes for each pay run, then files and pays your federal, state, and local payroll taxes based on the information you enter. It also generates W-2s and direct deposits and records every pay run in your books. See how FreshBooks Payroll works.
Frequently Asked Questions (FAQ)
Looking for more information on payroll tax withholding after learning the payroll tax definition and how much employer payroll taxes are? The following are some answers to the most frequently asked questions.
What is the formula for calculating payroll?
The basic formula for calculating payroll is:
Net pay = Gross pay - Deductions
Deductions can include payroll taxes, 401(k) contributions, health insurance premiums, and wage garnishments. Applicable state and local taxes also affect your payroll calculations.
What’s the easiest way to calculate payroll taxes as an employer?
If you want to save time on payroll tax calculations, payroll software is the best option. This is the easiest way to avoid calculation errors and keep important tax information organized and compliant.
What percentage of my paycheck is withheld for federal tax?
The percentage withheld for federal taxes depends on your filing status and income tax bracket. In addition to federal income taxes, you’ll pay 7.65% of your income in Medicare and Social Security taxes.
How often do employers need to pay their payroll taxes?
Unlike income tax, employers must send payroll taxes to the IRS either monthly or semi-monthly. This is in addition to filing quarterly federal tax returns. State payroll tax deadlines usually align with federal deadlines, but verify those deadlines in each state where you have employees.
How do you send payroll taxes to the IRS?
Send payroll taxes to the IRS via the Electronic Federal Tax Payment System (EFTPS). This free, paperless online payment method was created by the United States Treasury. Some states also require you to pay state taxes online.
What happens if my employer doesn’t pay payroll taxes?
If your employer doesn’t pay payroll taxes, your employer may face penalties and be personally liable for any taxes they withheld and didn’t pay. If you never get a W-2, use your pay stubs to file Form 4852.